Quick Answer
In the 1099 NEC vs 1099 MISC comparison, pay for services goes on Form 1099-NEC. Almost every other reportable payment — rent, royalties, prizes, medical bills — goes on Form 1099-MISC. For 2026, both forms use a $2,000 threshold for most payments. Form 1099-NEC is due to the worker and the IRS by February 1, 2027.
Introduction
The two forms look almost identical, and their names differ by only two letters. No wonder “1099 misc vs 1099 nec” is one of the most common questions every January.
Most people asking it are holding one specific payment and one deadline. This guide gives you the one-line rule, a payment-by-payment decision table, and the exact 2026 thresholds and dates.
For the full picture on every 1099 form, see our complete guide to 1099 forms and contractors.
1099-NEC vs 1099-MISC at a Glance
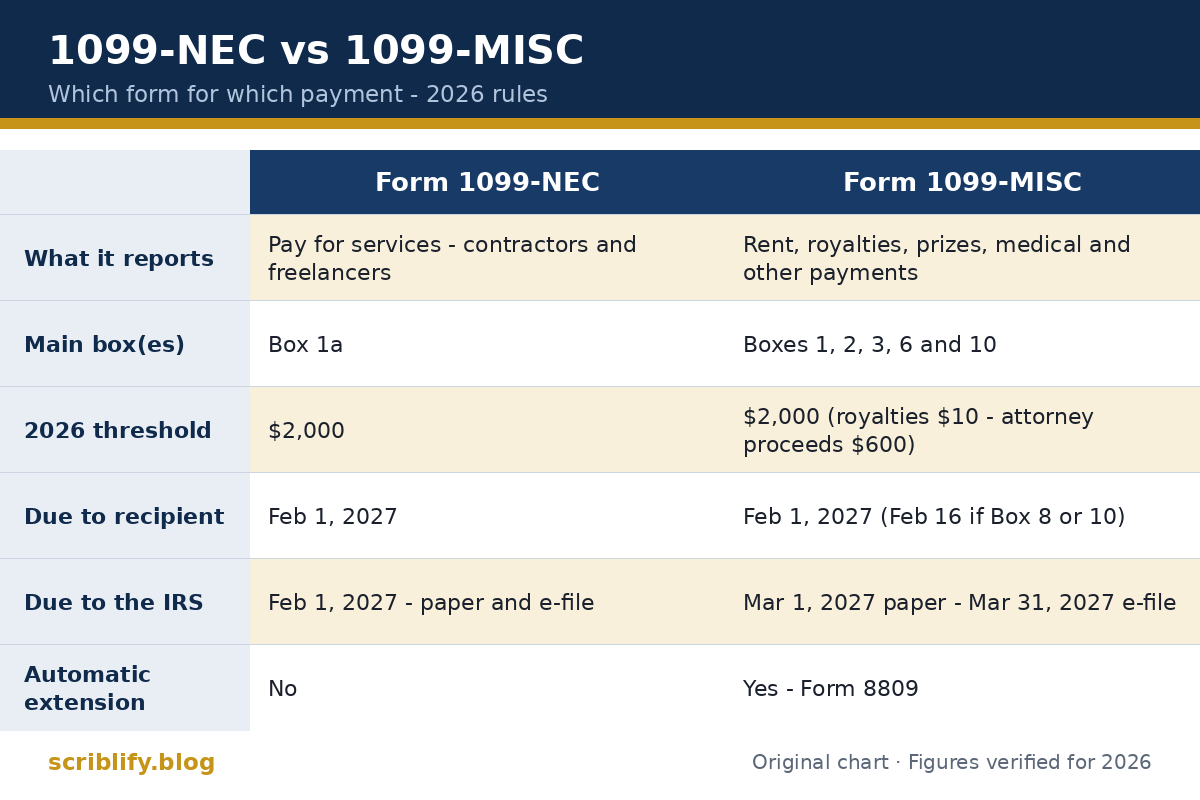
Here is the whole comparison on one screen. The sections below explain each row.
| Form 1099-NEC | Form 1099-MISC | |
|---|---|---|
| What it reports | Pay for services by nonemployees | Rent, royalties, prizes, medical and other payments |
| Common examples | Freelancers, contractors, consultants | Office rent, royalties, prizes, crop insurance |
| 2026 threshold | $2,000 | $2,000 (royalties $10; attorney proceeds $600) |
| Due to recipient | February 1, 2027 | February 1, 2027 (February 16 if Box 8 or 10 has amounts) |
| Due to the IRS | February 1, 2027 — paper and e-file | March 1, 2027 paper · March 31, 2027 e-file |
| Automatic extension | No | Yes — Form 8809 |
| The worker’s own taxes | NEC pay is usually subject to self-employment tax | MISC rent and royalty income usually is not |
Which Payments Go on Form 1099-NEC?
Form 1099-NEC reports money you paid a nonemployee for work. You file it when all four of these are true:
- The payment was for services.
- The person you paid is not your employee.
- You made the payment in the course of running your business.
- Your payments to that person total $2,000 or more for the year (for 2026).
Typical payments: freelance projects, contractor and subcontractor work, consulting, and professional services such as an attorney’s fee for legal work — reported in Box 1a.
Our full Form 1099-NEC guide walks through every box, the deadlines, and the penalties in detail.
Which Payments Go on Form 1099-MISC?
Form 1099-MISC covers most reportable payments that are not pay for services. The main ones:
- Rent — Box 1. Office, land, or equipment rent of $2,000 or more.
- Royalties — Box 2. Reported from just $10.
- Prizes and awards not for services — Box 3, along with other income.
- Medical and health care payments — Box 6. These are reported even when the payee is a corporation.
- Crop insurance proceeds — Box 9.
- Gross proceeds (a settlement or award paid to an attorney for a client) paid to an attorney — Box 10, from $600. This is a settlement payment, not the attorney’s fee.
- Fish purchases for resale — Box 11, from $600.
- Fishing boat proceeds — Box 5, at any amount.
Box 12 covers section 409A deferred compensation (optional to complete), and Box 15 covers nonqualified deferred compensation of $2,000 or more.
If a payment does not fit the services rule, it usually lands here — if it is reportable at all. Wondering whether a corporation gets a form at all? Our guide on whether S corps get a 1099 explains the corporate exemption and its exceptions.
Which Form Do You Use for This Payment?
Find your payment below — the form, the box, and the 2026 threshold for each one.
| Payment | Form | Box | 2026 threshold |
|---|---|---|---|
| Services by a freelancer, contractor, or consultant | 1099-NEC | 1a | $2,000 |
| Attorney’s fee for legal services | 1099-NEC | 1a | $2,000 |
| Attorney gross proceeds (legal settlement) | 1099-MISC | 10 | $600 |
| Rent for an office, land, or equipment | 1099-MISC | 1 | $2,000 |
| Royalties | 1099-MISC | 2 | $10 |
| Prize or award given for services | 1099-NEC | 1a | $2,000 |
| Prize or winnings not for services | 1099-MISC | 3 | $2,000 |
| Medical or health care payments | 1099-MISC | 6 | $2,000 |
| Crop insurance proceeds | 1099-MISC | 9 | $2,000 |
| Fish bought for resale | 1099-MISC | 11 | $600 |
| Fishing boat proceeds | 1099-MISC | 5 | Any amount |
| Direct sales of consumer products | 1099-NEC or 1099-MISC | 2 or 7 | $5,000 |
| Rent plus repair work from the same person | Both forms — split it | MISC 1 / NEC 1a | Each tested on its own |
| Contractor paid by card or payment app | Neither — the processor files Form 1099-K | — | — |
| A payment you applied backup withholding to | The form that fits the payment | — | Any amount |
Two rows trip people up. A prize paid for services is really pay for work, so it goes on the NEC. And a card-paid contractor gets no form from you at all — the payment processor reports that money itself.
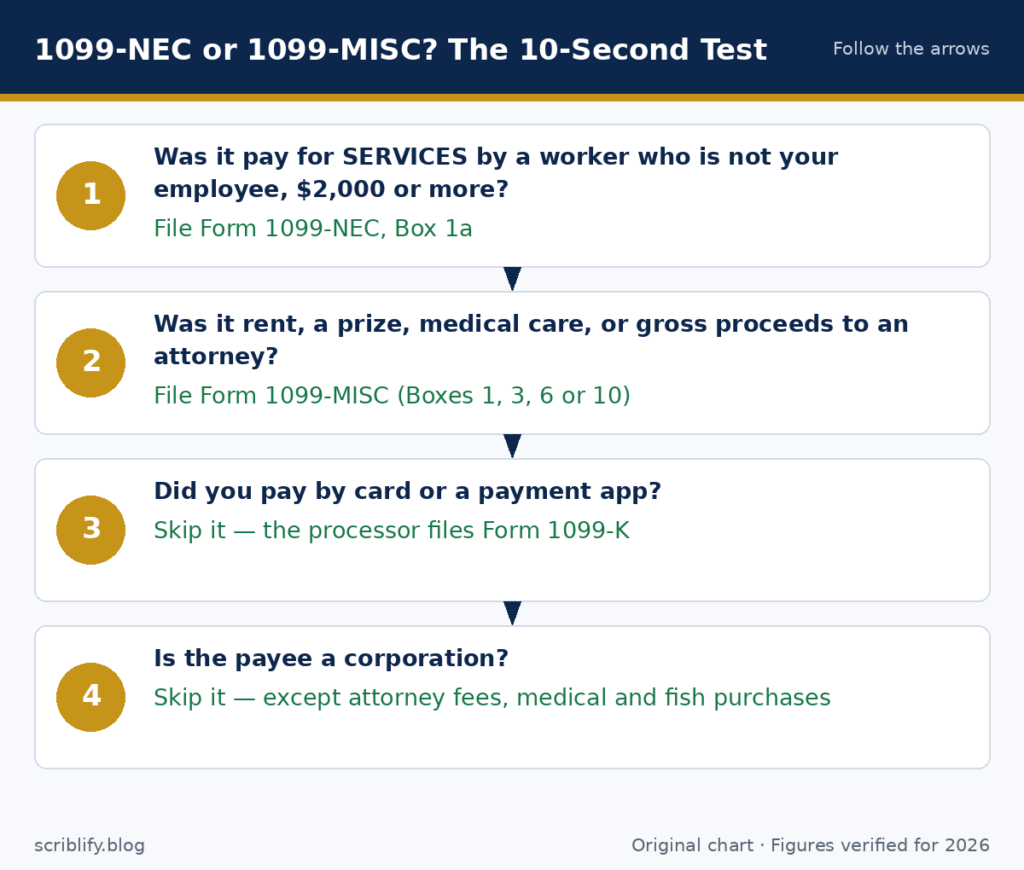
Which Form — the 10-Second Test
- Services only → Form 1099-NEC.
- Rent, prizes, medical or other MISC payments only → Form 1099-MISC.
- Both kinds paid to the same person → both forms.
- Neither (an employee, or merchandise only) → no form.
Why Are There Two Forms?
Before 2020, pay for services sat in Box 7 of Form 1099-MISC. Starting with tax year 2020, the IRS split it into its own form and brought back Form 1099-NEC.
The practical reason you feel today is the deadline. Contractor pay now has one early deadline — January 31 — while the rest of Form 1099-MISC kept its later filing dates.
One myth to drop: Form 1099-MISC was not discontinued. Most “1099-misc vs 1099-nec” confusion comes from old pages written before the split. Form 1099-MISC is still filed every year for rent, royalties, and the other payments above.
What Are the Thresholds for 2026?
For payments made on or after January 1, 2026, the reporting threshold rose from $600 to $2,000 for both forms and most payment types. The change came from the One Big Beautiful Bill Act (OBBBA). From 2027, the $2,000 figure is adjusted for inflation.
Payments made in 2025 or earlier still follow the old $600 rule. A few thresholds did not move:
| Payment type | Threshold | Where it goes |
|---|---|---|
| Royalties | $10 | 1099-MISC, Box 2 |
| Gross proceeds to an attorney | $600 | 1099-MISC, Box 10 |
| Fish purchases for resale | $600 | 1099-MISC, Box 11 |
| Direct sales | $5,000 | 1099-NEC Box 2 or 1099-MISC Box 7 |
| Fishing boat proceeds | Any amount | 1099-MISC, Box 5 |
| Payments with backup withholding | Any amount | The form that fits the payment |
Examples: 2025 vs 2026
Because the rule changed mid-stream, the year you paid matters more than the year you file:
| Example | Paid in 2025 ($600 rule) | Paid in 2026 ($2,000 rule) |
|---|---|---|
| $1,500 to a contractor for services | 1099-NEC required | No form required |
| $2,500 to a contractor for services | 1099-NEC required | 1099-NEC required |
| $1,500 rent to a landlord | 1099-MISC required | No form required |
When Is Each Form Due?
Both forms go to the recipient early. They part ways at the IRS deadline. These are the dates for tax year 2026:
| Deadline | Form 1099-NEC | Form 1099-MISC |
|---|---|---|
| Give to the recipient | February 1, 2027 | February 1, 2027 (February 16 if Box 8 or 10 has amounts) |
| File with the IRS — paper | February 1, 2027 | March 1, 2027 |
| File with the IRS — e-file | February 1, 2027 | March 31, 2027 |
The NEC dates moved because January 31, 2027 falls on a Sunday. Form 1099-NEC has no automatic extension — its January 31 deadline covers both furnishing and filing. Form 1099-MISC can get an automatic extension with Form 8809.
Filing 10 or more information returns in total makes e-filing mandatory. The IRS publishes both forms’ full rules in its instructions for Forms 1099-MISC and 1099-NEC.
One state note: many states receive Form 1099-NEC through the IRS Combined Federal/State Filing Program, while state treatment of Form 1099-MISC varies — check your own state’s rule before you file.
Need more time? For Form 1099-MISC, filing Form 8809 by the due date gives an automatic 30-day extension to file with the IRS. For Form 1099-NEC there is no automatic extension — Form 8809 only helps in hardship cases, and it must be signed and sent on paper.
What Changed on the Forms for 2026?
The split itself does not change in 2026. What changed is a few boxes: new boxes for tips and overtime appear on both forms, and one payment type moved house.
| Change for 2026 | Form 1099-NEC | Form 1099-MISC |
|---|---|---|
| Excess golden parachute payments | Now Box 3 | Was Box 14 |
| New box for cash tips | Box 1b | Box 13a |
| New box for tipped occupation codes | Box 1c | Box 13b |
| New box for overtime pay | Box 1d | Box 14 |
If you file from last year’s template, check these boxes first — an old layout is the easiest way to put a current payment in a stale box.
Can the Same Person Get Both Forms?
Yes — and it happens more often than people expect. Each form’s threshold is tested only against the payments that belong on that form.
Say you rent a small workshop from Maria. In 2026 you pay her:
- $9,600 in rent → Form 1099-MISC, Box 1. It passes the $2,000 threshold.
- $3,400 for repairs she did herself → Form 1099-NEC, Box 1a. The repair work is a service, and it passes $2,000 on its own.
Maria gets both forms from you. Now change one number: if the repairs had cost $1,500, no 1099-NEC would be due — even though you paid her more than $11,000 in total. The two amounts are never added together.
Payments to a foreign person for work done abroad are usually reported on Form 1042-S, not on a 1099.
What If You Filed the Wrong Form?
It is fixable, and fixing it early is cheap. The IRS procedure has three steps:
- Void the wrong form. File a corrected return on the form you used, with the CORRECTED box checked and the amount set to zero.
- File the right form as a new original. Not a correction — a fresh filing on the correct form, with the full amount.
- Send the recipient corrected copies, so their records match what the IRS now has.
Do not just file the second form and leave the first one standing — the IRS would count the payment twice.
Penalties make speed worthwhile. For 2026, filing late or incorrectly runs $60, then $130, then $340 per form, depending on how late the fix is — and $680 per form for intentional disregard. The IRS counts each copy separately. If the amounts are large or the deadline has passed, a CPA can file the corrections for you.
Got the Wrong Form From a Payer?
If a payer sent you the wrong form, ask them for a corrected copy first — most will fix it once they see the mistake.
If they refuse, report the income correctly on your own tax return anyway. Tax follows the income, not the form. Keep the form you received and a note of what you asked for, in case the IRS ever asks.
A Note on Form 1099-K
Money received through payment apps and cards is reported on Form 1099-K by the processor — for 2026, when payments pass more than $20,000 across more than 200 transactions. A 1099-K does not replace a 1099-NEC you owe a contractor; the two forms cover different payers.
Key Takeaways
- Services → Form 1099-NEC. Almost everything else reportable → Form 1099-MISC.
- For 2026, the main threshold is $2,000 on both forms — up from $600. Royalties ($10) and attorney gross proceeds ($600) stayed low.
- Form 1099-NEC is due everywhere by February 1, 2027, with no automatic extension. Form 1099-MISC files with the IRS by March 1 (paper) or March 31 (e-file), 2027.
- One person can get both forms. Each form’s threshold is tested on its own payments only.
- Filed the wrong form? Void it with a corrected $0 return, then file the right form as a new original.
Frequently Asked Questions
What is the main difference between 1099-NEC and 1099-MISC?
Form 1099-NEC reports pay for services — money you paid a nonemployee to do work. Form 1099-MISC reports most other reportable payments: rent, royalties, prizes, medical payments and similar items. For 2026 both forms use a $2,000 threshold for most payments, and each payment type is tested on its own.
1099 misc vs 1099 nec — which form does an attorney get?
It depends on what the payment was for. Fees you paid an attorney for legal services go on Form 1099-NEC, Box 1a, once they reach $2,000. Gross proceeds from a legal settlement go on Form 1099-MISC, Box 10, at the older $600 threshold, which the 2026 increase did not change.
Can the same person receive both a 1099-NEC and a 1099-MISC?
Yes. One person can receive both forms from you in the same year. If you paid a landlord $9,600 in rent and $3,400 for repairs she did herself, the rent goes on Form 1099-MISC and the repair work on Form 1099-NEC. Each form’s threshold is tested only against its own payments.
Do corporations or LLCs get a 1099 form?
Most payments to corporations are exempt from both forms, so no filing is needed. Two exceptions always apply: medical and health care payments are reported on Form 1099-MISC even if the payee is a corporation, and payments to attorneys are still reported. For LLCs, check the payee’s Form W-9 to see how the business is classified. A single-member LLC is usually a disregarded entity, so payments to it follow the owner’s rules, not a corporation’s.
What happens if I filed the wrong form?
File a corrected return on the wrong form with the CORRECTED box checked and the amount set to zero, which voids it. Then file the correct form as a new original, and send the recipient corrected copies. Penalties for 2026 run $60 to $340 per form, so fixing it early costs less.
Is Form 1099-MISC still used, or did 1099-NEC replace it?
Yes, Form 1099-MISC is still very much in use for rent, royalties, prizes, medical payments, crop insurance proceeds and several other payment types. Form 1099-NEC only took over one job — reporting pay for services — when the two forms split in 2020. Neither form replaced the other.
I paid my contractor by credit card — do I still file a 1099-NEC?
No. When you pay by credit card or through a payment platform, the payment processor reports the money on Form 1099-K instead. Filing a 1099-NEC as well would report the same income twice. The choice between the two forms only applies to payments you made directly.
What is the threshold for 2026 — is it still $600?
For most payments, the threshold is $2,000 for payments made in 2026, up from $600. The increase covers both forms. A few thresholds did not move: royalties are still reported at $10, gross proceeds to an attorney at $600, fish purchases at $600, and direct sales at $5,000.
I got a 1099-NEC but I don’t have a business — what does that mean?
It means the payer treated you as self-employed. You still report the income, usually on Schedule C, and you can deduct real business expenses against it. You do not need to form an LLC to file.
Does a 1099-NEC mean I am self-employed?
Usually, yes. NEC pay is compensation for services outside a job, and the IRS generally treats it as self-employment income — which is why self-employment tax applies.
How much tax will I pay on a 1099-MISC?
The income is taxed at your normal income tax rates, like most other income. Self-employment tax usually does not apply to rent, royalties or prizes reported on Form 1099-MISC. If the payment was really for services, it belongs on Form 1099-NEC instead — and then self-employment tax does apply. Either way, report the full amount on your return.
The Bottom Line
Pick the form by what the payment was for, not by who received it. Work gets Form 1099-NEC; rent, royalties, and the rest get Form 1099-MISC. Test each payment against its own 2026 threshold, and mind the one deadline that forgives nothing — February 1, 2027 for the NEC.
Working through a stack of year-end forms? Our complete guide to 1099 forms and contractors gathers every form, box, and deadline in one place.
This guide is educational and is not tax advice.
Leave a Reply