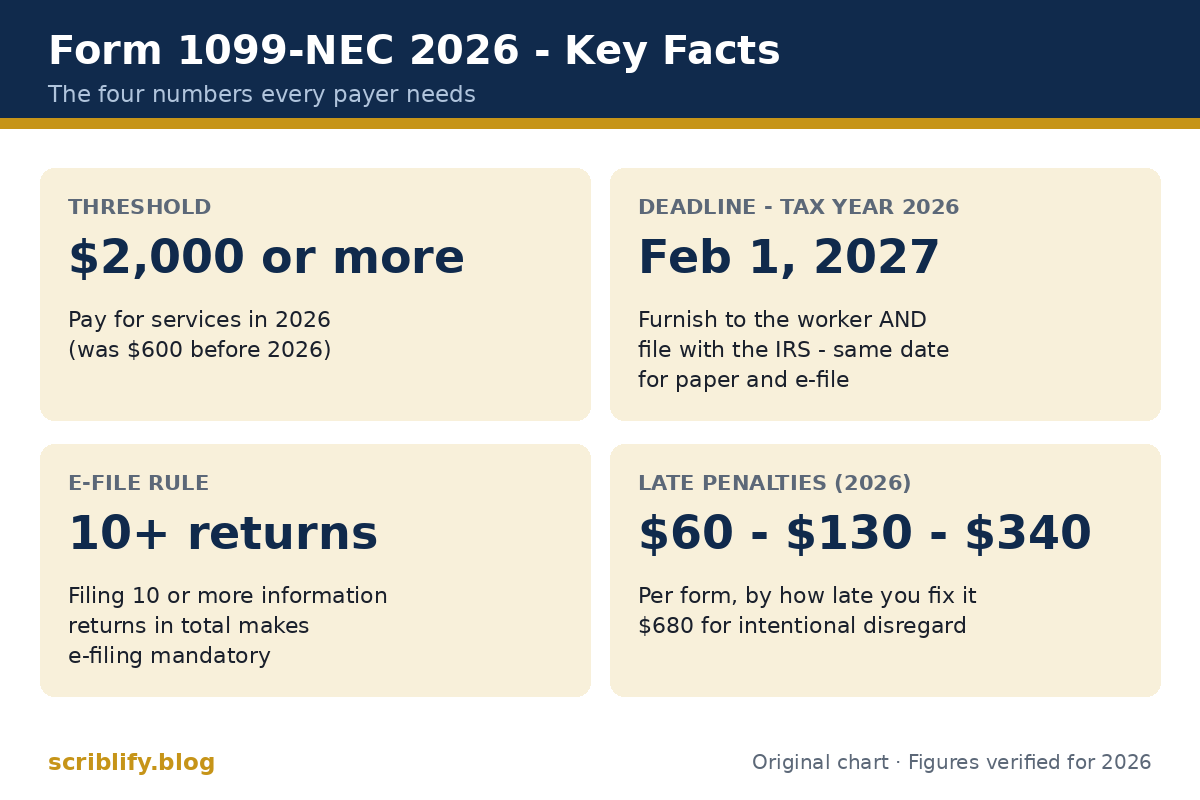
Quick answer: You must file Form 1099-NEC for 2026 if your business paid a contractor $2,000 or more — up from $600. Send Copy B to the contractor and file with the IRS by 1 February 2027. File electronically if you submit 10 or more information returns in total.
Form 1099-NEC is the form businesses use to report payments of $2,000 or more made to freelancers, contractors, and other non-employees in 2026. It tells the worker and the IRS exactly how much was paid for services.
The 2026 tax year brings the biggest change in years: the reporting threshold rises from $600 to $2,000. This guide explains what the form is, who must file, what goes in each box, the deadlines, and how to file step by step.
What Is Form 1099-NEC?
The official IRS page for Form 1099-NEC describes it as the form for nonemployee compensation: money a business pays for services performed by someone who is not its employee.
It serves two audiences. Payers file it to report what they paid. Recipients use their copy to check the amount and report the income on their tax return.
- Filed by the business that paid for the services.
- Sent to the worker (Copy B) and the IRS (Copy A).
- Covers services only — not wages, rents, or card payments.
What’s New for 2026?
For payments made after 31 December 2025, the reporting threshold is $2,000 — up from $600.
The change comes from the One Big Beautiful Bill Act. The new threshold will be adjusted for inflation starting in 2027.
| Before (payments through 2025) | Now (payments from 2026) |
|---|---|
| $600 reporting threshold | $2,000 reporting threshold |
Paid a designer $1,500 in 2026? No 1099-NEC is required. Paid them $2,000 or more? You must file one.
Who Must File a 1099-NEC?
You must file if your business paid $2,000 or more in 2026 for services, to a non-employee, in the course of your trade or business.
The IRS sets four conditions — all four must be true:
- You paid someone for services they performed.
- The payee was not your employee — including individuals, partnerships, and attorneys.
- The payment was in the course of your trade or business.
- The total paid to that person in 2026 was $2,000 or more.
- You withheld backup withholding from a payment — then you file for that payee no matter the amount.
Payments to corporations are generally exempt. One exception: fees for legal services still go on a 1099-NEC, even when the law firm is a corporation. (Medical or health care payments to a corporation are reported on Form 1099-MISC instead.)
Collect Form W-9 from every contractor before you pay them. If you have no taxpayer ID for a payee, you must apply 24% backup withholding to their payments.
Employee or Contractor?
A 1099-NEC is only for independent contractors. If you control what the worker does and how they do it, the IRS usually sees an employee — and employees get a W-2, not a 1099. Getting this wrong can cost back taxes and penalties.
1099-NEC Box by Box
Most filers only ever use Box 1a. Here is what each box on the December 2026 revision is for.
| Box | What goes in it |
|---|---|
| 1a | Nonemployee compensation — the total paid for services ($2,000 or more) |
| 1b | Cash tips received |
| 1c | Tipped-occupation codes |
| 1d | Overtime pay |
| 2 | Direct sales of $5,000 or more — tick the box if it applies |
| 3 | Excess golden parachute payments |
| 4 | Federal income tax withheld — usually 24% backup withholding |
| 5 | State tax withheld |
| 6 | State / payer’s state number |
| 7 | State income |
Boxes 5–7 exist for state tax departments. Most small businesses leave Boxes 1b–1d, 2, and 3 blank.
What counts in Box 1a?
Include: fees, commissions, and other pay for services — including parts and materials supplied as part of the service. Do not include: payments for merchandise alone, rent (that goes on Form 1099-MISC), or pay to employees (that goes on Form W-2).
A Filled-In Example (Sample)
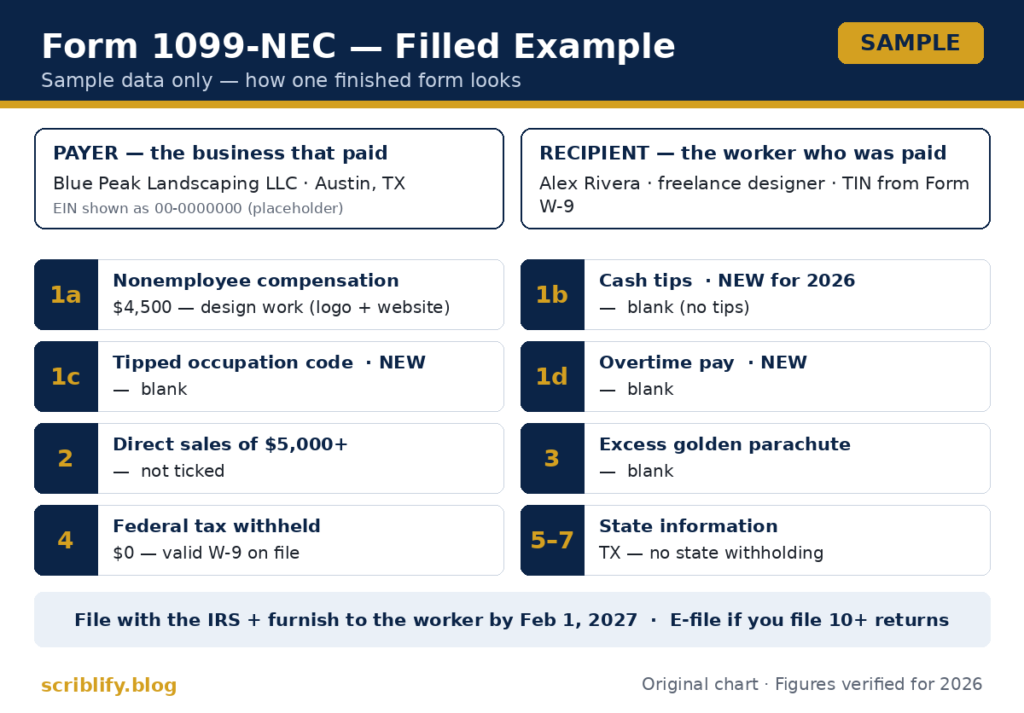
One form covers one contractor for the whole year.
Sample only — not a real filing. Blue Peak Landscaping LLC paid Alex Rivera, a freelance designer, $4,500 for design work in 2026.
| Box | Entry |
|---|---|
| Payer details | Blue Peak Landscaping LLC — name, address, and TIN from its own records |
| Recipient details | Alex Rivera — name, address, and TIN copied from Form W-9 |
| Box 1a | $4,500 |
| Boxes 1b–1d | Blank — no tips or overtime |
| Box 2 | Unticked — no direct sales |
| Box 3 | Blank — no golden parachute payment |
| Box 4 | Blank — Alex provided a TIN, so no backup withholding |
| Boxes 5–7 | Blank — no state withholding in this sample |
Because the $4,500 total clears the $2,000 threshold, Blue Peak must file this form.
The yearly total is what counts — if smaller payments only reach $2,000 in December, you still file.
How to File Form 1099-NEC, Step by Step
Get a W-9, total the year’s payments, fill in the form, file Copy A with the IRS, send Copy B to the worker, and keep Copy C.
- Collect Form W-9 from the contractor before you pay them — never in January.
- Add up everything you paid them in 2026. At $2,000 or more, you file.
- Fill in the form, copying names and TINs exactly from the W-9.
- File Copy A with the IRS — e-file through IRS IRIS (IRIS is the IRS’s current e-filing system — it has replaced the old FIRE system.), or mail paper forms with Form 1096.
- Send Copy B to the contractor by 1 February 2027.
- Keep Copy C in your own records for at least four years.
Know your copies:
| Copy | Goes to |
|---|---|
| A | The IRS |
| B | The recipient — the contractor |
| C | You — the payer keeps it |
| 1 | The state tax department |
| 2 | The recipient — for their state filing |
Filing on paper? Mail Copy A of every form to the IRS with Form 1096 — one transmittal per form type.
Where do you mail a paper Form 1099-NEC?
Filing on paper (only allowed if you file fewer than 10 information returns in total)? Send Copy A with Form 1096 — one Form 1096 for each form type — flat, in a large envelope, to the IRS center for your state:
- AL, AZ, AR, DE, FL, GA, KY, ME, MA, MS, NH, NJ, NM, NY, NC, OH, TX, VT, VA, or outside the US: Internal Revenue Service, P.O. Box 149213, Austin, TX 78714-9213
- AK, CO, HI, IA, ID, IL, IN, KS, MI, MN, MO, MT, ND, NE, NV, OK, OR, SC, SD, TN, UT, WA, WI, WY: Internal Revenue Service Center, P.O. Box 219256, Kansas City, MO 64121-9256
- CA, CT, DC, LA, MD, PA, RI, WV: Internal Revenue Service Center, 1973 North Rulon White Blvd., Ogden, UT 84201
One warning: Copy A must be the official red-ink form. You cannot print Copy A from the IRS website — the IRS scanners cannot read it. Order the official forms free from the IRS, or buy them from an office-supply store. The fill-in versions on IRS.gov work only for the copies you give to recipients (Copies 1, B and 2).
1099-NEC Deadlines for Tax Year 2026
For the 2026 tax year, both dates fall on 1 February 2027 — 31 January is a Sunday.
| What | Deadline |
|---|---|
| Furnish Copy B to the recipient | 1 February 2027 |
| File with the IRS (paper and e-file) | 1 February 2027 — the same day |
Unlike some other 1099s, the NEC has no later IRS filing date. Treat 1 February as the one deadline that matters.
Penalties for Late or Incorrect Filing
The IRS charges per form, and the amount grows the longer you wait to fix it.
| How late | Penalty per form |
|---|---|
| Fixed within 30 days of the deadline | $60 |
| Fixed after 30 days but by 1 August | $130 |
| Fixed after 1 August — or never filed | $340 |
| Intentional disregard | $680 |
Small businesses get lower annual caps on these penalties — but even a few late forms add up fast.
Need more time? Form 1099-NEC has no automatic extension. You can request 30 extra days to file with the IRS on Form 8809, but only on paper, signed, and only for a real hardship — such as a disaster, a fire, or the death or serious illness of the person responsible for filing. For more time to give copies to recipients, use Form 15397.
How to Correct a 1099-NEC Mistake
File a corrected form marked CORRECTED.
Spotted an error after filing? Prepare a new form with the right figures, tick the CORRECTED box, and file Copy A with the IRS again — paper filers include a fresh Form 1096. Then send a corrected Copy B to the recipient, who needs it for their own return.
Fix mistakes quickly. The sooner you correct, the lower the penalty tier.
Use VOID only when you filed a duplicate form for the same payee by mistake in the same filing run. Never check the VOID box on a corrected form — the IRS will not enter a correction that has VOID checked.
Common 1099-NEC Mistakes
Most errors come from old habits and outdated guides.
- Using the old $600 threshold for 2026 payments.
- Reporting service payments on Form 1099-MISC instead of Form 1099-NEC.
- Missing the 1 February deadline because you assumed paper filing gets 28 February.
- Paying contractors before collecting Form W-9.
- Reporting credit-card or platform payments on 1099-NEC — those belong on Form 1099-K.
- Forgetting state filing — many states want their own copy.
A Note on State Filing
Filing with the IRS does not always satisfy your state.
Many states require their own copy of the form or a direct state filing, and the rules vary by state. Check your state revenue department’s guidance before you assume the federal filing is enough.
Received a 1099-NEC? What to Do
Report the income — whether or not a form arrived.
- Report Box 1a income on Schedule C, Profit or Loss from Business.
- Pay self-employment tax of 15.3% on your net profit.
- Make quarterly estimated tax payments with Form 1040-ES, since nothing was withheld.
- Got no form but earned the money? You still report all of it. The $2,000 figure is the payer’s filing threshold, not a tax-free allowance.
Keep track of your deductible expenses through the year — our small business tax deductions guide lists the ones contractors claim most.
1099-NEC vs 1099-MISC
The NEC reports payments for services; the MISC reports rents and other payments.
| Form 1099-NEC | Form 1099-MISC | |
|---|---|---|
| What it reports | Nonemployee compensation — payments for services | Rents, prizes, royalties, and other payments |
| 2026 threshold | $2,000 or more | $2,000 or more |
| Deadline (2026 tax year) | 1 February 2027 — same date for paper and e-file | Furnish by 1 February 2027; file 1 March 2027 on paper or 31 March 2027 by e-file |
Putting service payments on the MISC — or card payments on the NEC — is one of the most common filing errors. If a payment could belong on either form, our 1099-NEC vs 1099-MISC comparison puts every payment type, box, and deadline side by side.
Key Takeaways
- The 2026 reporting threshold is $2,000, up from $600.
- Furnish Copy B and file with the IRS by 1 February 2027.
- E-file if you file 10 or more information returns in total.
- Box 1a holds the service payments; most filers touch nothing else.
- Collect W-9s before you pay — no TIN means 24% backup withholding.
- Card and platform payments go on Form 1099-K, not 1099-NEC.
Paying a corporation instead of a person? Corporations are usually exempt from 1099 reporting — see do S corps get a 1099 for the rules and exceptions.
Frequently Asked Questions
What is the 1099-NEC form for?
Form 1099-NEC reports payments a business makes to non-employees for services — freelancers, contractors, and sole traders. The payer files Copy A with the IRS and sends Copy B to the worker. For 2026, you file it when payments to one person total $2,000 or more.
What is the new 1099-NEC limit for 2026?
For payments made in 2026, the reporting threshold is $2,000 — up from $600. The change comes from the One Big Beautiful Bill Act and applies to payments after 31 December 2025. The threshold will be adjusted for inflation starting in 2027.
When is Form 1099-NEC due?
For the 2026 tax year, Form 1099-NEC is due on 1 February 2027. You must furnish Copy B to the recipient and file Copy A with the IRS by that date. The same date applies whether you file on paper or electronically.
Who is required to receive a 1099-NEC?
A contractor or freelancer must receive a 1099-NEC if a business paid them $2,000 or more for services in 2026. This includes individuals, partnerships, and most LLCs. Payments to corporations are generally exempt. One exception: fees for legal services still go on a 1099-NEC, even when the law firm is a corporation. (Medical or health care payments to a corporation are reported on Form 1099-MISC instead.)
Do I have to pay taxes on a 1099-NEC?
Yes. A 1099-NEC reports taxable income. You owe income tax on your profit plus 15.3% self-employment tax on net earnings. The payer does not withhold tax for you, so you may need to make quarterly estimated payments using Form 1040-ES.
How do I report 1099-NEC income on my taxes?
Report Box 1a income on Schedule C, Profit or Loss from Business. Deduct your business expenses there to find your net profit. Then calculate self-employment tax on Schedule SE. Attach both schedules to your Form 1040 when you file your return.
What if I have a 1099-NEC but no business?
A 1099-NEC does not require a registered business. Many recipients are sole traders by default. Report the income on Schedule C as a sole proprietor, claim your related expenses, and pay self-employment tax on the profit. Keep simple records of what you earned and spent.
Does a 1099-NEC mean I am self-employed?
Usually, yes. Receiving a 1099-NEC means a business treated you as an independent contractor, not an employee. That makes you self-employed for tax purposes: you report the income on Schedule C and pay self-employment tax. If you believe you were really an employee, you can ask the IRS for a ruling.
What happens if I file a 1099-NEC late?
The IRS charges a penalty for each late form. For 2026 filings it is $60 per form if corrected within 30 days, $130 if corrected by 1 August, and $340 after that. Intentional disregard costs at least $680 per form. Penalties apply per form, so several late filings add up quickly.
What is the difference between 1099-NEC and 1099-MISC?
Form 1099-NEC reports payments for services to non-employees, such as freelancers and contractors. Form 1099-MISC reports other payments, like rents, prizes, and royalties. For 2026, the NEC is due 1 February 2027 for both paper and e-file, while the MISC gets later IRS dates.
Where do you get Form 1099-NEC?
Order the official paper forms free from the IRS at IRS.gov/OrderForms or by phone, or buy them at an office-supply store — order early, because Copy A must be the printed red-ink version. You can also download fill-in copies from IRS.gov for the recipient copies (Copies 1, B and 2), or skip paper entirely and e-file through IRIS (IRIS is the IRS’s current e-filing system — it has replaced the old FIRE system.).
Do you have to file a 1099-NEC on your taxes?
Yes. If you received a 1099-NEC, the income goes on your tax return — usually on Schedule C. Report it even if you never received the form; the work is still taxable income.
How much tax do you pay on a 1099-NEC?
There is no single 1099 rate. You pay income tax on your profit at your normal rate, plus self-employment tax of 15.3% on 92.35% of your net earnings. Business expenses lower both.
Why did I get a 1099-NEC instead of a W-2?
Your payer treated you as an independent contractor, not an employee. If the business sets your hours, provides your tools and controls how you do the work, you may be misclassified. You can ask the IRS to decide by filing Form SS-8, and report the pay with Form 8919 so you pay only the employee share of Social Security and Medicare tax.
Conclusion
Form 1099-NEC looks fiddly, but it comes down to three numbers: the $2,000 threshold, the 1 February 2027 deadline, and Box 1a. Get those right and the rest is routine.
For the full picture — every 1099 type, worker classification rules, and state quirks — read our 1099 forms and contractors guide.
This guide is educational and is not tax advice.
Leave a Reply